
Florida Backing-Up Accident Claims After a Driver Hits You
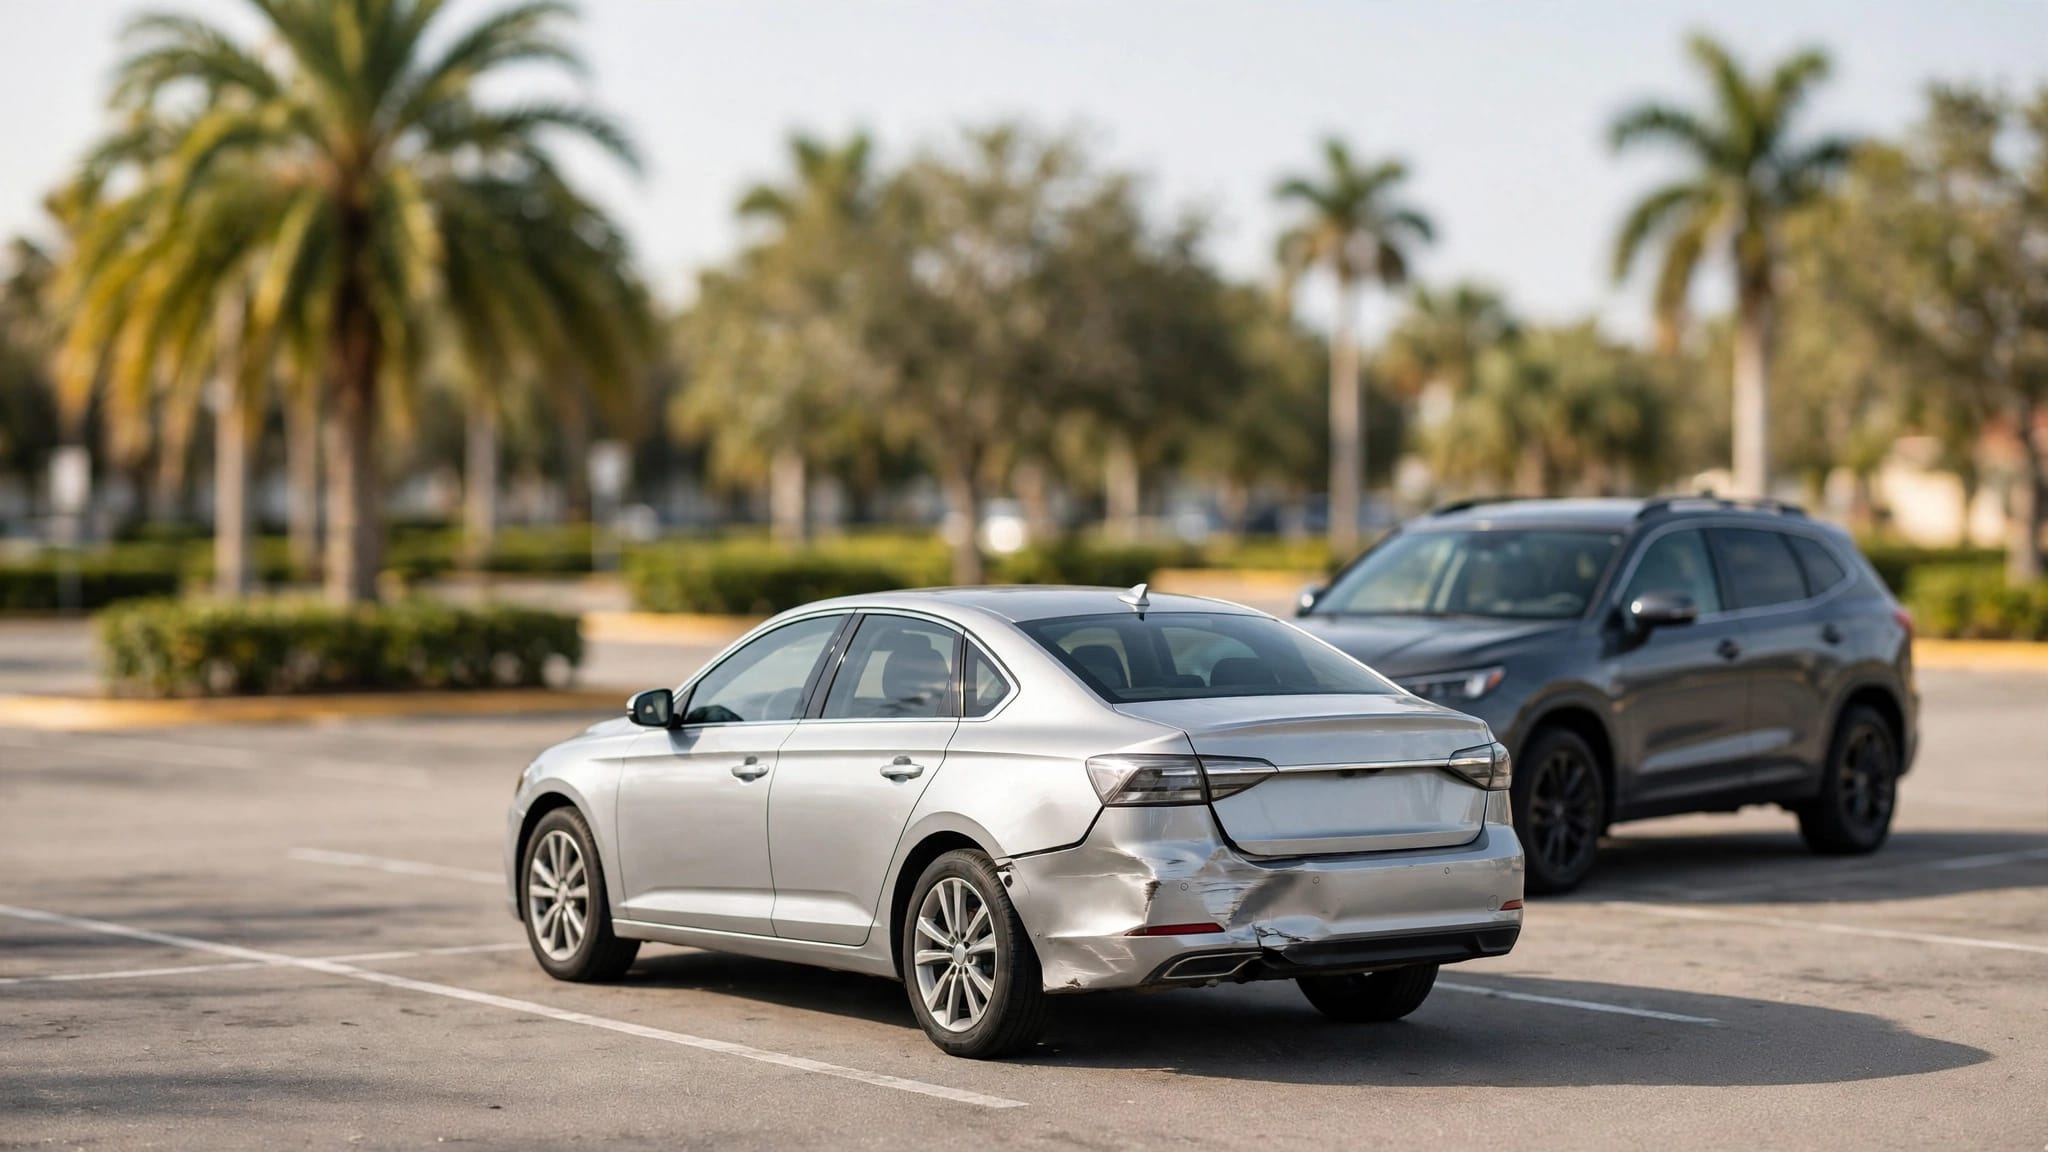
A driver reverses into your car, then tells the insurer you should have moved. A Florida backing-up accident can turn into a fault dispute even when the direction of travel seems clear. What happened before impact matters as much as where the vehicles ended up.
If you were injured, you also have medical and insurance deadlines to manage while that dispute unfolds. Start with the rule for backing up, then preserve the evidence that shows how the collision happened.
Key Takeaways
- Florida requires drivers to back up only when they can do so safely and without interfering with other traffic. That rule doesn’t automatically decide every claim.
- Photos, independent witnesses, video, and vehicle damage can help establish who moved where before impact.
- If you’re injured, seek care promptly. Florida’s Personal Injury Protection (PIP) rules generally require initial medical services within 14 days.
- PIP may cover part of your medical expenses and lost income, while vehicle damage and other injury losses require separate attention.
- Shared fault can reduce a negligence recovery. In covered cases, being more than 50% at fault can bar it.
What Florida law requires when a driver backs up
The driver must check that the movement is safe
Under Florida’s traffic rules for backing vehicles, section 316.1985 prohibits backing unless the driver can do it safely and without interfering with other traffic. The rule applies beyond parking lots. A driver leaving a driveway or reversing along a street must also account for vehicles in the intended path.
That duty doesn’t disappear because the driver has a backup camera or audible warning system. Those features may help, but the driver still needs to look and respond to what is there.
A violation doesn’t settle every fault question
A backing driver may face a strong liability claim after striking a vehicle traveling through a parking aisle. Yet the details can change the analysis. Did the other car enter the aisle while the driver was already reversing? Were both vehicles moving backward? Did one driver pull into the other’s path?
A citation, if issued, can be useful evidence. It doesn’t require an insurer or court to accept one account without examining the rest of the scene. In a Florida backing-up accident, the strongest account connects the driver’s movement to the point of impact.
Fault in a Florida backing-up accident
The impact location is a starting point
Damage patterns can help establish the sequence of events. A vehicle’s rear bumper against another car’s side may fit an account of a driver reversing into passing traffic. Scrapes, paint transfer, and the positions of the cars can add context.
Still, damage alone rarely tells the whole story. A car may be stopped, creeping forward, or turning when struck. Photos taken before either vehicle moves are especially useful because they preserve lane position and the space available to each driver.
Shared fault can change the claim
Florida applies comparative fault rules to many negligence claims. If you’re found 20% responsible for your damages, a $50,000 recovery would generally fall to $40,000 before other claim issues. In a covered negligence action, a person found more than 50% at fault generally cannot recover damages.
An insurer might claim you were speeding through a lot or turned too close to a reversing car. Ask what supports that account. Camera footage, sight lines, witness observations, and vehicle positions matter more than an unsupported percentage. Learn more about how shared fault affects Florida crash claims before accepting an adjuster’s assessment.
Evidence that helps when accounts conflict
Preserve the scene and find independent witnesses
If it’s safe, photograph both vehicles before they move. Include wide shots of the parking spaces or roadway, closer views of damage, license plates, signs, and any blocked sight lines. In a parking lot, record whether the cars were inside marked spaces or traveling through an aisle.
Get contact information from people who saw the movement before impact. A witness who only heard the collision may still help, but someone who saw when each vehicle started moving can answer a more important question.
Nearby businesses or homes may have camera footage. Ask promptly whether video exists and request that it be preserved. Save original dashcam files as well, rather than relying on a shortened clip.
Obtain the report, but keep your own records
Call 911 when someone is injured or the crash creates a hazard, and follow instructions at the scene. If an officer investigates, obtain the report information. Florida Highway Safety and Motor Vehicles provides crash report and insurance guidance for drivers.
A report may identify drivers, witnesses, and an officer’s observations. It can also contain incomplete or disputed accounts. Write down your own timeline while the details are fresh, including where you were, whether you had stopped, and when you first saw the reversing vehicle.
The absence of an officer’s report doesn’t automatically end a claim. Photos, witnesses, video, and repair records become more important when pursuing a claim without a police report.
Medical care and PIP after a backing crash
Don’t wait for the insurers to decide fault
Some injuries are easier to notice after the initial shock wears off. Seek medical attention for symptoms such as neck pain, headaches, dizziness, numbness, or reduced movement. Tell the provider when each symptom began and how the collision occurred.
Florida’s PIP benefit statute generally requires initial services and care within 14 days of the crash for medical benefits. Treatment during that period doesn’t guarantee that every bill will be paid. Waiting beyond it can jeopardize available PIP benefits.
Keep discharge papers, prescriptions, imaging results, therapy records, bills, and work restrictions. These documents show both the care you received and how the injury affected your daily life.
Know what PIP does and doesn’t pay
Florida drivers generally must carry at least $10,000 in PIP coverage. Under the state’s automobile insurance overview, PIP generally pays 80% of covered, necessary medical expenses and 60% of lost income, subject to statutory conditions and limits. Medical benefits may be limited to $2,500 without a qualifying emergency medical condition determination.
PIP can provide benefits without first proving who caused the wreck. It doesn’t decide liability, pay to repair your car, or cover pain and suffering. Those are separate claim questions.
Compensation beyond initial medical benefits
Vehicle damage follows a different insurance path
If another driver caused the collision, their property damage liability coverage may pay for your vehicle repairs and related losses, subject to proof and policy limits. Florida generally requires $10,000 in property damage liability coverage. A repair estimate, towing receipt, photographs, and records of reasonable transportation costs help document what you seek.
You may also have collision coverage under your own policy. Check your deductible and ask how your insurer will handle recovery from the other carrier. If the car may be a total loss, keep records of its condition, mileage, and recent work.
Don’t assume PIP will pay for any of this. Vehicle damage and injury benefits run through different coverage.
Serious injuries may support a separate claim
A claim against the at-fault driver may address losses PIP doesn’t fully pay, including additional medical expenses and lost earning capacity. Depending on the injury and available coverage, it may also include pain and suffering.
Florida limits recovery of certain non-economic damages after motor vehicle crashes to injuries that meet a legal threshold. Permanent injury, significant and permanent loss of an important bodily function, and significant permanent scarring are among the statutory categories. Medical records are central to proving Florida’s serious injury threshold.
The backing driver may lack enough insurance to cover a serious injury claim. If you carry uninsured or underinsured motorist coverage, review whether it applies rather than assuming the other driver’s policy is your only option.
What to do before giving an insurer your account
Report accurately without guessing
Notify your insurer promptly and follow your policy’s reporting requirements. Give a clear account of what you saw, where your car was, and what happened next. If you don’t know the other driver’s speed or the exact distance between vehicles, say so.
Be careful with a detailed recorded statement to the other driver’s insurer while evidence is still missing. A rough estimate can later conflict with video or measurements. Likewise, an adjuster’s early fault decision isn’t the final word when new evidence becomes available.
Keep the claim file complete
Save repair estimates, photos, medical bills, pay records, and every letter from an insurer. Note the date of each conversation and what the adjuster requested. If a business confirms that it has video, record who you spoke with and when.
Review any settlement offer against your actual losses. An injury release may end the claim before the need for further treatment or time away from work becomes clear. When the other driver denies backing into you, evidence for a disputed car accident claim can help identify what needs closer review.
Filing deadlines and when legal help matters
For negligence claims arising from crashes on or after March 24, 2023, Florida’s statute of limitations for negligence generally allows two years to file a lawsuit. Older claims or unusual circumstances may have different deadlines. An open insurance claim or settlement discussion doesn’t automatically stop the clock.
That filing period is separate from PIP’s 14-day treatment requirement and any notice terms in your policy. Check Florida’s car accident lawsuit deadlines early, particularly if fault or injuries remain disputed.
An attorney can help investigate conflicting accounts, request preservation of video, review available policies, and assess an offer before you sign a release. That review is especially useful when the insurer assigns you fault without clear support.
Frequently Asked Questions
Is the backing driver always at fault? No. Florida requires safe backing, but the evidence determines how that rule applies. Both drivers’ movements and any shared fault may matter.
Can I make a claim if the crash happened in a parking lot? Yes. Preserve the location, vehicle positions, damage, and witness information. Insurance coverage and fault still need review.
What if my symptoms appear the next day? Get evaluated promptly and explain when they began. Florida’s PIP rules generally require initial medical services within 14 days of the collision.
Can I pursue a claim without a police report? A report isn’t a universal prerequisite for an insurance claim. Notify your insurer, preserve other evidence, and check whether reporting rules applied to your crash.
A Clearer Path After a Backing Crash
The fact that another driver was reversing is important, but it isn’t the entire claim. Preserved evidence shows how the vehicles moved, while medical and financial records show what the collision cost you.
Seek care without waiting for a fault decision. Then evaluate the vehicle damage, available coverage, and any injury claim before accepting a settlement.